Millions Recovered
Uninsured Motorist Coverage Connecticut: What It Covers, Requirements, and Claim Process Explained
Last Updated - October 14, 2026
Read Time - Ex: 14 minutes
- Key Takeaways
- What Is Uninsured Motorist Coverage in Connecticut?
- Why This Matters
- Underinsured Motorist Insurance CT: What It Is and When It Applies
- The Gap Concept
- Why CT Drivers Consider Higher Limits
- How UM/UIM Limits Work in Connecticut
- How to Choose a Limit
- Reviewing Your Declarations Page
- UM vs. UIM: Examples That Make It Click
- Scenario 1: Hit-and-run with injuries
- Scenario 2: At-fault driver admits they have no insurance
- Scenario 3: At-fault driver has state-minimum coverage, but your injuries are serious
- Scenario 4: Multi-car crash with multiple injured people
- UIM Claim Process Connecticut: Step-by-Step Guide
- Step 1: Get Medical Care and Document Injuries
- Step 2: Report the Crash and Collect Evidence
- Step 3: Notify Your Insurer Early
- Step 4: Confirm the At-Fault Driver’s Insurance Limits
- Step 5: Track Your Damages
- Step 6: Coordinate Settlement With the At-Fault Insurer
- Step 7: Submit the UIM Demand Package
- Step 8: Negotiation and Resolution
- Step 9: Watch Deadlines and Paperwork
- Common Pain Points and How to Avoid Them
- When to Consider Legal Help
- How to Choose UM/UIM Limits in Connecticut
- Annual review checklist:
- Quick Glossary
- Key Takeaways
- FAQ
Key Takeaways
- Uninsured Motorist (UM) covers your injuries when the at-fault driver has no insurance or cannot be identified.
- Underinsured Motorist (UIM) helps when the at-fault driver’s limits are insufficient to cover your damages.
- Document everything — medical records, police reports, photos, and a clear symptom journal matter.
- Review your declarations page regularly and consider higher UM/UIM limits to protect income and assets.
- If a claim becomes disputed or injuries are serious, consider getting legal advice early.
You can do everything right on the road and still end up in a crash caused by someone else. What happens next depends largely on whether that other driver has insurance — and whether they have enough of it.
Uninsured motorist coverage Connecticut drivers carry on their own policies exists precisely for this situation. It’s a form of protection that pays for your injuries when the at-fault driver has no insurance, their insurer denies the claim, or the driver flees the scene entirely. Underinsured motorist insurance CT policies offer works similarly, stepping in when the other driver’s coverage isn’t enough to cover your losses.
This article explains what these coverages actually do, how they differ, and walks through the UIM claim process Connecticut residents should understand if they’re ever in this position. Whether you’re reviewing your current policy or dealing with a crash right now, this information can help you make better decisions.
What Is Uninsured Motorist Coverage in Connecticut?
Uninsured motorist coverage—often abbreviated as “UM”—is part of your own auto insurance policy. It can compensate you and your passengers when you’re injured by a driver who has no liability insurance at all.
This coverage typically applies in three situations:
- The at-fault driver has no auto insurance
- The at-fault driver’s insurer denies coverage (for example, due to a lapsed policy)
- The at-fault driver is unknown, such as in a hit-and-run
When we say “insured person” in this context, we’re usually talking about the named policyholder, family members living in the same household, and passengers riding in the covered vehicle at the time of the crash. That said, policy definitions vary. If you want to know exactly who’s covered under your policy, look at the “Definitions” section of your declarations page or call your insurer.
One common point of confusion: UM coverage is not the same as collision coverage. Collision pays to repair your car regardless of who caused the crash. UM focuses on injuries — your medical bills, lost wages, and pain and suffering — when the other driver can’t pay.
Why This Matters
Medical treatment after a car crash adds up quickly. An emergency room visit with imaging, follow-up appointments, physical therapy, and time away from work can easily reach tens of thousands of dollars. If the person who caused the crash has no insurance, you generally can’t collect from them personally unless they have significant assets — which is rarely the case.
UM coverage fills that gap. It’s there so you’re not left covering those costs on your own.
Underinsured Motorist Insurance CT: What It Is and When It Applies
Underinsured motorist coverage—usually called “UIM”—is closely related to UM, but it kicks in under different circumstances.
UIM applies when the at-fault driver does have insurance, but their policy limits aren’t high enough to cover your damages.
Here’s the simplest way to remember the difference:
- UM = the other driver has no insurance (or can’t be identified)
- UIM = the other driver has insurance, but not enough
The Gap Concept
Imagine you’re seriously injured in a crash caused by another driver. Your medical bills, lost wages, and other damages total $100,000. The at-fault driver carries the state minimum for bodily injury liability—let’s say $25,000.
You recover that $25,000 from their insurer. But you’re still $75,000 short.
If you have UIM coverage on your own policy, it may help cover some or all of that remaining amount, up to your policy’s UIM limits. The exact calculation depends on Connecticut rules and your specific policy language, but that’s the basic idea.
Why CT Drivers Consider Higher Limits
State-minimum liability limits exist to ensure every driver has at least some coverage. But minimums don’t reflect the real cost of serious injuries. A single surgery, a week in the hospital, or several months of physical therapy can exceed minimum limits before you’ve even accounted for lost income or ongoing care.
Carrying higher UIM limits on your own policy gives you more protection when someone else’s coverage falls short.
How UM/UIM Limits Work in Connecticut
Insurance limits can seem confusing at first, but they follow a straightforward structure.
Bodily injury limits are usually expressed as two numbers separated by a slash — for example, 50/100. This means:
- Up to $50,000 per injured person
- Up to $100,000 total per accident (if multiple people are hurt)
Your UM and UIM coverages have their own limits, which you select when you buy or renew your policy. These limits directly affect how much protection you have.
How to Choose a Limit
A common approach is to match your UM/UIM limits to your own liability limits. If you carry $100,000/$300,000 in liability coverage, consider carrying the same for UM/UIM.
When deciding what makes sense for your situation, think about:
- Your health insurance deductible and out-of-pocket maximum
- How much income you’d lose if you couldn’t work for weeks or months
- The potential cost of long-term rehabilitation or ongoing care
- Whether you have assets you want to protect
Reviewing Your Declarations Page
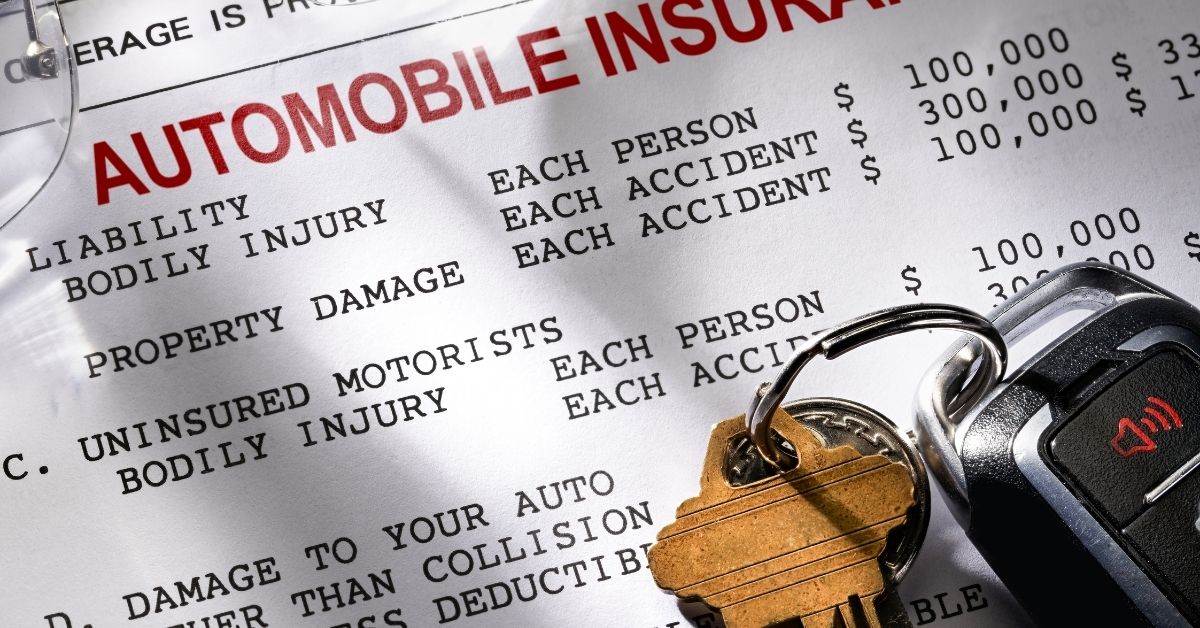
Your declarations page (sometimes called the “dec page”) is the summary of your policy. It lists your coverages and limits. Here’s what to look for:
- UM bodily injury limits – This is your protection against uninsured drivers
- UIM bodily injury limits – This is your protection against underinsured drivers
- Stacking – Some policies allow you to “stack” coverage across multiple vehicles, which can increase your available limits. Ask your insurer whether stacking applies to your policy and how it works.
If you’re not sure what you’re looking at, call your agent or insurer and ask them to walk you through it.
UM vs. UIM: Examples That Make It Click
Abstract definitions only go so far. Here’s how these coverages work in practice.
Scenario 1: Hit-and-run with injuries
You’re stopped at a red light when another car rear-ends you and drives off. You didn’t get the license plate. Your neck and back are injured.
Coverage that applies: UM. The other driver is unknown, so you’d file a claim under your own uninsured motorist coverage. Learn more about phantom driver claims.
Scenario 2: At-fault driver admits they have no insurance
Another driver runs a stop sign and hits your car. At the scene, they admit they let their policy lapse. You have a broken wrist and need surgery.
Coverage that applies: UM. The other driver has no valid insurance, so your UM coverage would respond.
Scenario 3: At-fault driver has state-minimum coverage, but your injuries are serious
A distracted driver crosses the center line and hits you head-on. They have $25,000 in bodily injury liability. Your injuries require hospitalization, multiple surgeries, and months of rehab. Total damages exceed $150,000.
Coverage that applies: UIM. The other driver has insurance, but it’s not nearly enough. After recovering their $25,000 limit, you’d turn to your own UIM policy for the remainder.
Scenario 4: Multi-car crash with multiple injured people
A driver causes a chain-reaction crash involving three vehicles. Several people are hurt. The at-fault driver has $100,000 per accident in liability coverage, but total injuries across all victims far exceed that.
Coverage that applies: UIM may be relevant. When the at-fault driver’s per-accident limit is exhausted, each injured person may need to look to their own UIM coverage for additional compensation. More on chain-reaction liability.
What This Means for You: UM and UIM are safety nets. They exist because the other driver’s ability to pay—or lack thereof—shouldn’t determine whether you can afford medical care or replace lost income.
UIM Claim Process Connecticut: Step-by-Step Guide
If you’re hurt in a crash and the at-fault driver doesn’t have enough coverage, understanding the UIM claim process in Connecticut can help you protect your rights. Here’s how it typically works.
Step 1: Get Medical Care and Document Injuries
Your health comes first. Seek medical attention promptly, even if your injuries seem minor at first. Some injuries—like soft tissue damage or concussions—don’t always show symptoms immediately.
Keep copies of everything: discharge paperwork, doctor’s notes, prescriptions, bills, and receipts for out-of-pocket expenses. These records form the foundation of your claim.
Step 2: Report the Crash and Collect Evidence
Call the police and make sure a crash report is filed. Get a copy of that report as soon as it’s available. What to do at the scene.
At the scene (if you’re able), take photos of the vehicles, the road, any visible injuries, and the surrounding area. Write down the names and contact information of any witnesses.
Step 3: Notify Your Insurer Early
Most auto policies require you to report accidents promptly. Contact your insurance company and provide the basic facts: when and where the crash happened, who was involved, and that you were injured.
Stick to what you know. Avoid speculating about fault or downplaying your injuries. You don’t need to have all the answers in this first call.
Step 4: Confirm the At-Fault Driver’s Insurance Limits
Your UIM claim depends in part on what coverage the other driver has. Work with your insurer or the at-fault driver’s insurer to confirm their bodily injury liability limits.
In some cases, you may need to request a copy of their declarations page. Your adjuster can help guide this process.
Step 5: Track Your Damages
Damages in personal injury cases fall into two categories:
Economic damages:
- Medical bills (past and anticipated future treatment)
- Lost wages
- Rehabilitation costs
- Out-of-pocket expenses (travel to appointments, assistive devices, etc.)
Non-economic damages:
- Physical pain
- Limitations on daily activities
- Sleep problems, anxiety, or emotional distress
- Loss of enjoyment of life — pain and suffering resources
Keep organized records. A simple symptom journal — noting your pain levels, what activities you can’t do, and how you’re feeling day to day — can be valuable later.
Step 6: Coordinate Settlement With the At-Fault Insurer
In many UIM cases, you’ll need to resolve the claim against the at-fault driver’s insurer before your UIM coverage fully applies. This often means settling their liability claim first.
Here’s the important part: your own insurer may need to consent before you finalize that settlement. This is often required under UIM policies. Check your policy language and ask your adjuster directly.
Skipping this step can create problems later.
Step 7: Submit the UIM Demand Package
Once you’ve resolved or are resolving the underlying claim, you’ll submit a demand package to your own insurer for UIM benefits.
This typically includes:
- The police crash report
- All medical records and bills
- Documentation of lost wages
- Photos from the scene
- A written narrative explaining how the crash happened, what injuries you sustained, and how they’ve affected your life
Step 8: Negotiation and Resolution
Your insurer will review your demand and respond — often with a counteroffer. From there, it’s a negotiation.
If you can’t reach agreement, most UIM policies include provisions for appraisal or arbitration. In some cases, litigation becomes necessary. The path forward depends on your policy terms and the specifics of the dispute.
Step 9: Watch Deadlines and Paperwork
Insurance policies include deadlines — for reporting claims, submitting documents, and responding to requests. Missing these deadlines can jeopardize your coverage.
Ask your insurer to put all requirements in writing. Keep copies of everything you send and receive.
Common Pain Points and How to Avoid Them
- Waiting too long to treat: Delays in seeking medical care can raise questions about whether your injuries are as serious as claimed.
- Gaps in care: If you stop treatment and then resume weeks later, insurers may argue you weren’t really injured — or that something else caused your symptoms.
- Signing releases too early: Be cautious about signing anything that could waive your rights before you fully understand your injuries and damages.
- Not understanding offsets or limits: UIM claims can involve complex calculations about how much you’re entitled to recover. If the numbers aren’t clear, ask questions.
When to Consider Legal Help
Not every UIM claim requires an attorney. But certain situations warrant professional guidance:
- Serious or long-term injuries
- Disputed fault
- Lowball settlement offers
- Confusing policy language
- Pressure to settle quickly
An experienced attorney can help you understand your options and advocate on your behalf.
How to Choose UM/UIM Limits in Connecticut
Buying auto insurance isn’t something most people think about until they need it. But spending a few minutes reviewing your coverages can make a significant difference if you’re ever in a crash.
Annual review checklist:
- Review your UM and UIM limits at least once a year
- Revisit your coverage after major life changes (new job, new vehicle, teen driver in the household)
- Consider raising limits if you have income or assets to protect
- Ask your agent: “What are my current UM/UIM limits? Is stacking available? Does my policy include uninsured motorist property damage?”
Keep digital and paper copies of your policy documents somewhere accessible. You don’t want to be searching for your declarations page while sitting in an emergency room.
Quick Glossary
- UM (Uninsured Motorist): Coverage for injuries caused by a driver with no insurance
- UIM (Underinsured Motorist): Coverage for injuries when the at-fault driver’s insurance isn’t enough
- Bodily Injury: Physical harm to a person (as opposed to property damage)
- Limits: The maximum amount your policy will pay for a covered claim
- Stacking: Combining coverage limits across multiple vehicles on the same policy
Key Takeaways
Uninsured motorist coverage protects you when the other driver has no insurance. Underinsured motorist insurance CT drivers carry protects you when the other driver’s coverage isn’t enough. Both are part of your own policy — not the other driver’s.
Understanding the UIM claim process Connecticut residents face can help you avoid common mistakes: document everything, notify your insurer promptly, and be careful about deadlines and settlements.
Your next steps:
- Check your declarations page for your current UM/UIM limits
- Ask your insurer how a UM or UIM claim would work under your specific policy
- If you’ve already been in a crash, start documenting and contact your insurer right away
“This article is for informational purposes only and does not constitute legal advice.” Every situation is different, and insurance policies vary. If you have questions about a specific claim or legal matter, consult with a qualified attorney.
FAQ
1. Is UM or UIM required in Connecticut?
Connecticut requires certain minimum coverages for drivers, but UM/UIM specifics can vary by policy and endorsement. Check your declarations page or ask your agent for the exact requirements that apply to your policy.
2. How do I start a UIM claim in Connecticut?
Report the crash to your insurer, seek medical care, gather evidence (police report, photos, medical records), confirm the at-fault driver’s limits, and submit a demand package to your own insurer when appropriate.
3. Can I stack UM/UIM limits in Connecticut?
Some policies and situations allow stacking across vehicles; others do not. The only way to know for sure is to review your policy language or ask your insurer directly — and consider the impact on your premiums and available coverage.
4. What if the insurer offers a quick settlement?
Be cautious. Quick offers can be tempting but may undervalue your long-term medical needs and non-economic damages. If injuries are significant or there is disagreement about value, consult an attorney before signing releases.
5. How long do I have to file a UM/UIM claim?
Deadlines vary by policy and state law. Prompt reporting is essential — report the accident immediately and ask your insurer for any timelines you must meet in writing.
- 1 30+ Years of Combined Experience
- 2 Millions Recovered for Injured Clients
- 3 No Fees Unless We Win
Share your information, and our team will be in touch.
Our Practice Areas
- Personal Injury
- Car Accidents
- Catastrophic Injury
- Defective Products
- Dog Bites
- Medical Malpractice
- Motorcycle Accidents
- Nursing Home Neglect
- Pedestrian Accidents
- Slip and Fall
- Traumatic Brain Injury
- Truck Accidents
- Wrongful Death
Case Results
-
Rear-End Collision
$850,000
-
Tractor Trailer Accident
$1,600,000
-
Wrongful Death Judgment
$24,500,000
Judgment against drunk driver in wrongful death case.
-
Auto v. Auto Accident
$600,000
-
Car Crash
$100,000
Hand injury caused during automobile crash.
-
Commercial Motor Vehicle Collision
$2,490,000
-
Automobile Collision
$500,000
Case involving automobile collision resulting in serious bodily injuries.
-
Motor Vehicle Collision
$1,200,000
Award from arbitration.
-
Soft Tissue Settlement
$300,000
Low velocity soft tissue settlement.
-
Motor Vehicle Crash
$600,000
Involving spinal injury.
-
Dog Bite Injuries
$600,000
-
Car Accident
$100,000
Policy limit settlement for nose injury from airbag deployment.
-
Mediated Settlement
$155,000
Mediated settlement in case involving complex claims of injury.
-
Hit and Run Highway Crash
$395,000
-
Head-On Car Crash
$285,000
Leg injury following head-on car crash.
Posted on Google![]()
Katie F3 days agoTrustindex verifies that the original source of the review is Google.
Amazing experience great staff. Would highly recommend to anyone who has been injured and see for yourselfPosted on Google![]()
Alyssa F3 days agoTrustindex verifies that the original source of the review is Google.
Awesome outcome thanks so much !!Posted on Google![]()
Gabriel L3 days agoTrustindex verifies that the original source of the review is Google.
They are great at what they do ,,, life changing great , Ron and Lue are like the Jorden and Rodman of personal injury !!!! Vote for Lue !!!!Posted on Google![]()
Donald D8 days agoTrustindex verifies that the original source of the review is Google.
Enemies law is real professional they actually care about there clients they call me every month with a update of my case and make sure I am alright as a person also they have put me in contact with Dr's that actually help you Thank you for your servicePosted on Google![]()
Donald D10 days agoTrustindex verifies that the original source of the review is Google.
I want to start out by thanking Etemi Law firm for a exceptional job first of all top notch job. I went to Etemi Law Firm with just a picture of a out of state license plate and some personal injuries I was involved in a hit and run accident on 95 first they got me lined up with the right Drs to help me with my recovery then they started there job in no time they had the driver of the truck that hit me but also the company the truck was leased to that was in Texas good investigating I had Attorney Semir Dervisi he did a fantastic job all the way to the mediation hearing he wasn't taking nothing less then I deserved and he did everything he said he was going to do we went over my case serval times so I knew exactly what was going on and if your lucky enough to get Michelle as your paralegal you got the best she called me every month just to check on me in my recovery make sure I was getting all the right treatments I needed,answered any questions I had she would answer and if she didn't have the answer she would get with the attorney to get it and call me back she is wonderful hard working lady. I would highly recommend Etemi if you need a attorney that caresPosted on Google![]()
Wislyne N26 days agoTrustindex verifies that the original source of the review is Google.
I had a great experience, I have no complaints. It was such a smooth process. Michelle is so so sweet, she was so communicative and understanding and patient with me. Ron is also awesome!!Posted on Google![]()
Isidro R42 days agoTrustindex verifies that the original source of the review is Google.
Lou and Nicole were an absolute blessing and have helped me out so much! Love them both!Posted on Google![]()
Jennifer S47 days agoTrustindex verifies that the original source of the review is Google.
Amazing service… pleasure to work with the whole team to get max payout.Posted on Google![]()
Ahmed I48 days agoTrustindex verifies that the original source of the review is Google.
I had a great experience with Etemi Law throughout the entire process. They were very professional, patient, and always kept me informed every step of the way. They genuinely cared about my situation and made the process much easier and less stressful for me. I truly appreciate their hard work, communication, and dedication. I would definitely recommend Etemi Law to anyone looking for a personal injury lawyer.Posted on Google![]()
Aljbnor T140 days agoTrustindex verifies that the original source of the review is Google.
Etemi law is the best! I had attorney Lou And paralegal Michelle and they got the job done. I highly recommend them to anyone in an accident!Posted on Google![]()
Heaven H147 days agoTrustindex verifies that the original source of the review is Google.
I had a great experience working with Etemi Law. They were professional, knowledgeable, and always kept me informed throughout the process. They took the time to answer my questions and made me feel confident every step of the way. I truly appreciate their hard work and dedication. From start to finish, my lawyer went above and beyond for me. They were responsive, compassionate, and fought hard for the best outcome. I felt supported during a stressful time and am very grateful for their help. Would highly recommend them to anyone needing legal assistancePosted on Google![]()
Anisa B158 days agoTrustindex verifies that the original source of the review is Google.
Best place to go too!!Posted on Google![]()
Kimberly C159 days agoTrustindex verifies that the original source of the review is Google.
Everyone was very friendly. I Was very satisfied with Lou Etemi.Posted on Google![]()
Victor J174 days agoTrustindex verifies that the original source of the review is Google.
Ron ( lawyer)at Etemi Law helped us alot in our case. He was honest and very informational as this was our first case. If I needed a lawyer again I would go through Etemi Law. I have nothing but the best things to say about them. Very pleased. Each n every member of this law firm professional n courteous, specialy Ms VE, always kept us informed about casePosted on Google![]()
Bijt E178 days agoTrustindex verifies that the original source of the review is Google.
Etemi law is the best firm ever. Michelle is the bomb. I highly recommend them as a firm to anyone! Best attorneys ever!Posted on Google![]()
Loue E184 days agoTrustindex verifies that the original source of the review is Google.
Outstanding experiencePosted on Google![]()
Samir D193 days agoTrustindex verifies that the original source of the review is Google.
I was involved in a serious crash and Etemi Law went above and beyond to help me through the process. They were with me every step of the way. If you are ever in need of an attorney, this is the firm that I recommend. They care about communication and they care about their clients. Ron and V were there for me from the beginning and I am super grateful. Highly recommend!!Posted on Google![]()
Yameci196 days agoTrustindex verifies that the original source of the review is Google.
Attorneys are amazing here! Will 100% recommend them to anyone in need of lawyers ☺️Posted on Google![]()
Clams196 days agoTrustindex verifies that the original source of the review is Google.
Very very grateful I was referred to Etemi Law. Lou, Ron & Michelle made me feel like family, and this may sound crazy but I’m going to miss them. I can tell you with certainty that they are all great at what they do, and I would not hesitate at all to recommend them to friends and family. 100% the best, not even a close second to Etemi Law.Posted on Google![]()
Steve D196 days agoTrustindex verifies that the original source of the review is Google.
I was referred to Lou Etemi by close friend and they were extremely professional. I’m very grateful for the way they handled me personally and my case they were very personable and they carried a great deal about how I felt and they treated me like family.Posted on Google![]()
Jefrey R210 days agoTrustindex verifies that the original source of the review is Google.
I can’t say enough great things about Lou and his entire team. From the very beginning, they treated me with professionalism, respect, and genuine care. After my car accident, I was stressed and unsure about the process, but Lou and his crew made everything feel manageable and kept me informed every step of the way. Their communication was excellent, always answering my questions and making sure I understood what was going on. You can tell they truly fight for their clients and don’t settle for less than what you deserve. Thanks to their hard work and dedication, they were able to reach a settlement for my case, and I couldn’t be more grateful. If you’re looking for an attorney who is knowledgeable, responsive, and truly has your best interests at heart, I highly recommend Lou and his team. They really go above and beyond.Posted on Google![]()
Derek C213 days agoTrustindex verifies that the original source of the review is Google.
Ron and V were the best possible team to land with when I was hit head on. I was referred to Etemi by a friend, somewhat out of necessity, and again...can't imagine I would have had a better support team or outcome. Not only did they educate me on the process, but also understood and planned for how insurance companies are trained to approach my specific case. If you are in a serious accident, Etemi deserves an interview to handle your situation. Thanks again guys.
Etemi Law Injury Lawyers
Founded by Waterbury natives Ron and Lou Etemi, our firm is deeply connected to the communities we serve. We bring determined advocacy and proven results to serious injury cases across Connecticut.